Monday, February 23, 2015

THINKING OF BUYING? WHAT ARE YOU WAITING FOR?

Thinking of Buying? What are you waiting for?

Thinking of Buying? What Are You Waiting For? | Simplifying The Market
If you are planning on becoming a homeowner, or moving up to the home of your dreams in 2015, here are four great reasons to consider buying a home now, instead of waiting until spring.

1. Prices Will Continue to Rise

The Home Price Expectation Survey polls a distinguished panel of over 100 economists, investment strategists, and housing market analysts. Their most recent report projects appreciation in home values over the next five years to be between 11.7% (most pessimistic) and 27.5% (most optimistic).
The bottom in home prices has come and gone. Home values will continue to appreciate for years. Waiting no longer makes sense.

2. Mortgage Interest Rates Are Projected to Increase

Although Freddie Mac’s Primary Mortgage Market Survey shows that interest rates for a 30-year mortgage have softened recently, most experts predict that they will begin to rise over the next 12 months. The Mortgage Bankers Association, Fannie Mae, Freddie Mac & the National Association of Realtors are in unison projecting that rates will be up almost a full percentage point by the end of 2015.
An increase in rates will impact YOUR monthly mortgage payment. Your housing expense will be more a year from now if a mortgage is necessary to purchase your next home.

3. Either Way You are Paying a Mortgage

As a paper from the Joint Center for Housing Studies at Harvard University explains:
“Households must consume housing whether they own or rent. Not even accounting for more favorable tax treatment of owning, homeowners pay debt service to pay down their own principal while households that rent pay down the principal of a landlord plus a rate of return. That’s yet another reason owning often does—as Americans intuit—end up making more financial sense than renting.”

4. It’s Time to Move On with Your Life

The ‘cost’ of a home is determined by two major components: the price of the home and the current mortgage rate. It appears that both are on the rise.
But, what if they weren’t? Would you wait?
Look at the actual reason you are buying and decide whether it is worth waiting. Whether you want to have a great place for your children to grow up, you want your family to be safer or you just want to have control over renovations, maybe it is time to buy.

If the right thing for you and your family is to purchase a home this year, buying sooner rather than later could lead to substantial savings.

When you wonder how this applies to your unique situation call, text or email.
 

Friday, February 20, 2015

AN IDEA OF WHEN TO LIST YOUR HOME FOR SALE

Do you want your home to stand out or get lost in lots of competition? The circled dates are the 10 actual dates when the most listings come on the market.
I know it's cold outside but people are still looking at and buying homes every day.

For how this can work in your unique situation call, text or email.

Thursday, February 19, 2015

Don't Over Think Get the Facts

Are you in this group??
Don't assume!!! I can put you in touch with real live lenders who can give you answers that can't be found by believing what you see in the media.

Wednesday, February 18, 2015

WHAT IS HAPPENING WITH OWNERSHIP RATES?

Homeownership Rates: Are they Crashing?

Homeownership Rates: Are They Crashing? | Simplifying The Market
The Census recently released their 2014 Homeownership Statistics, and many began to worry that Americans have taken a step back from the notion of homeownership.

Easy… Chicken Little

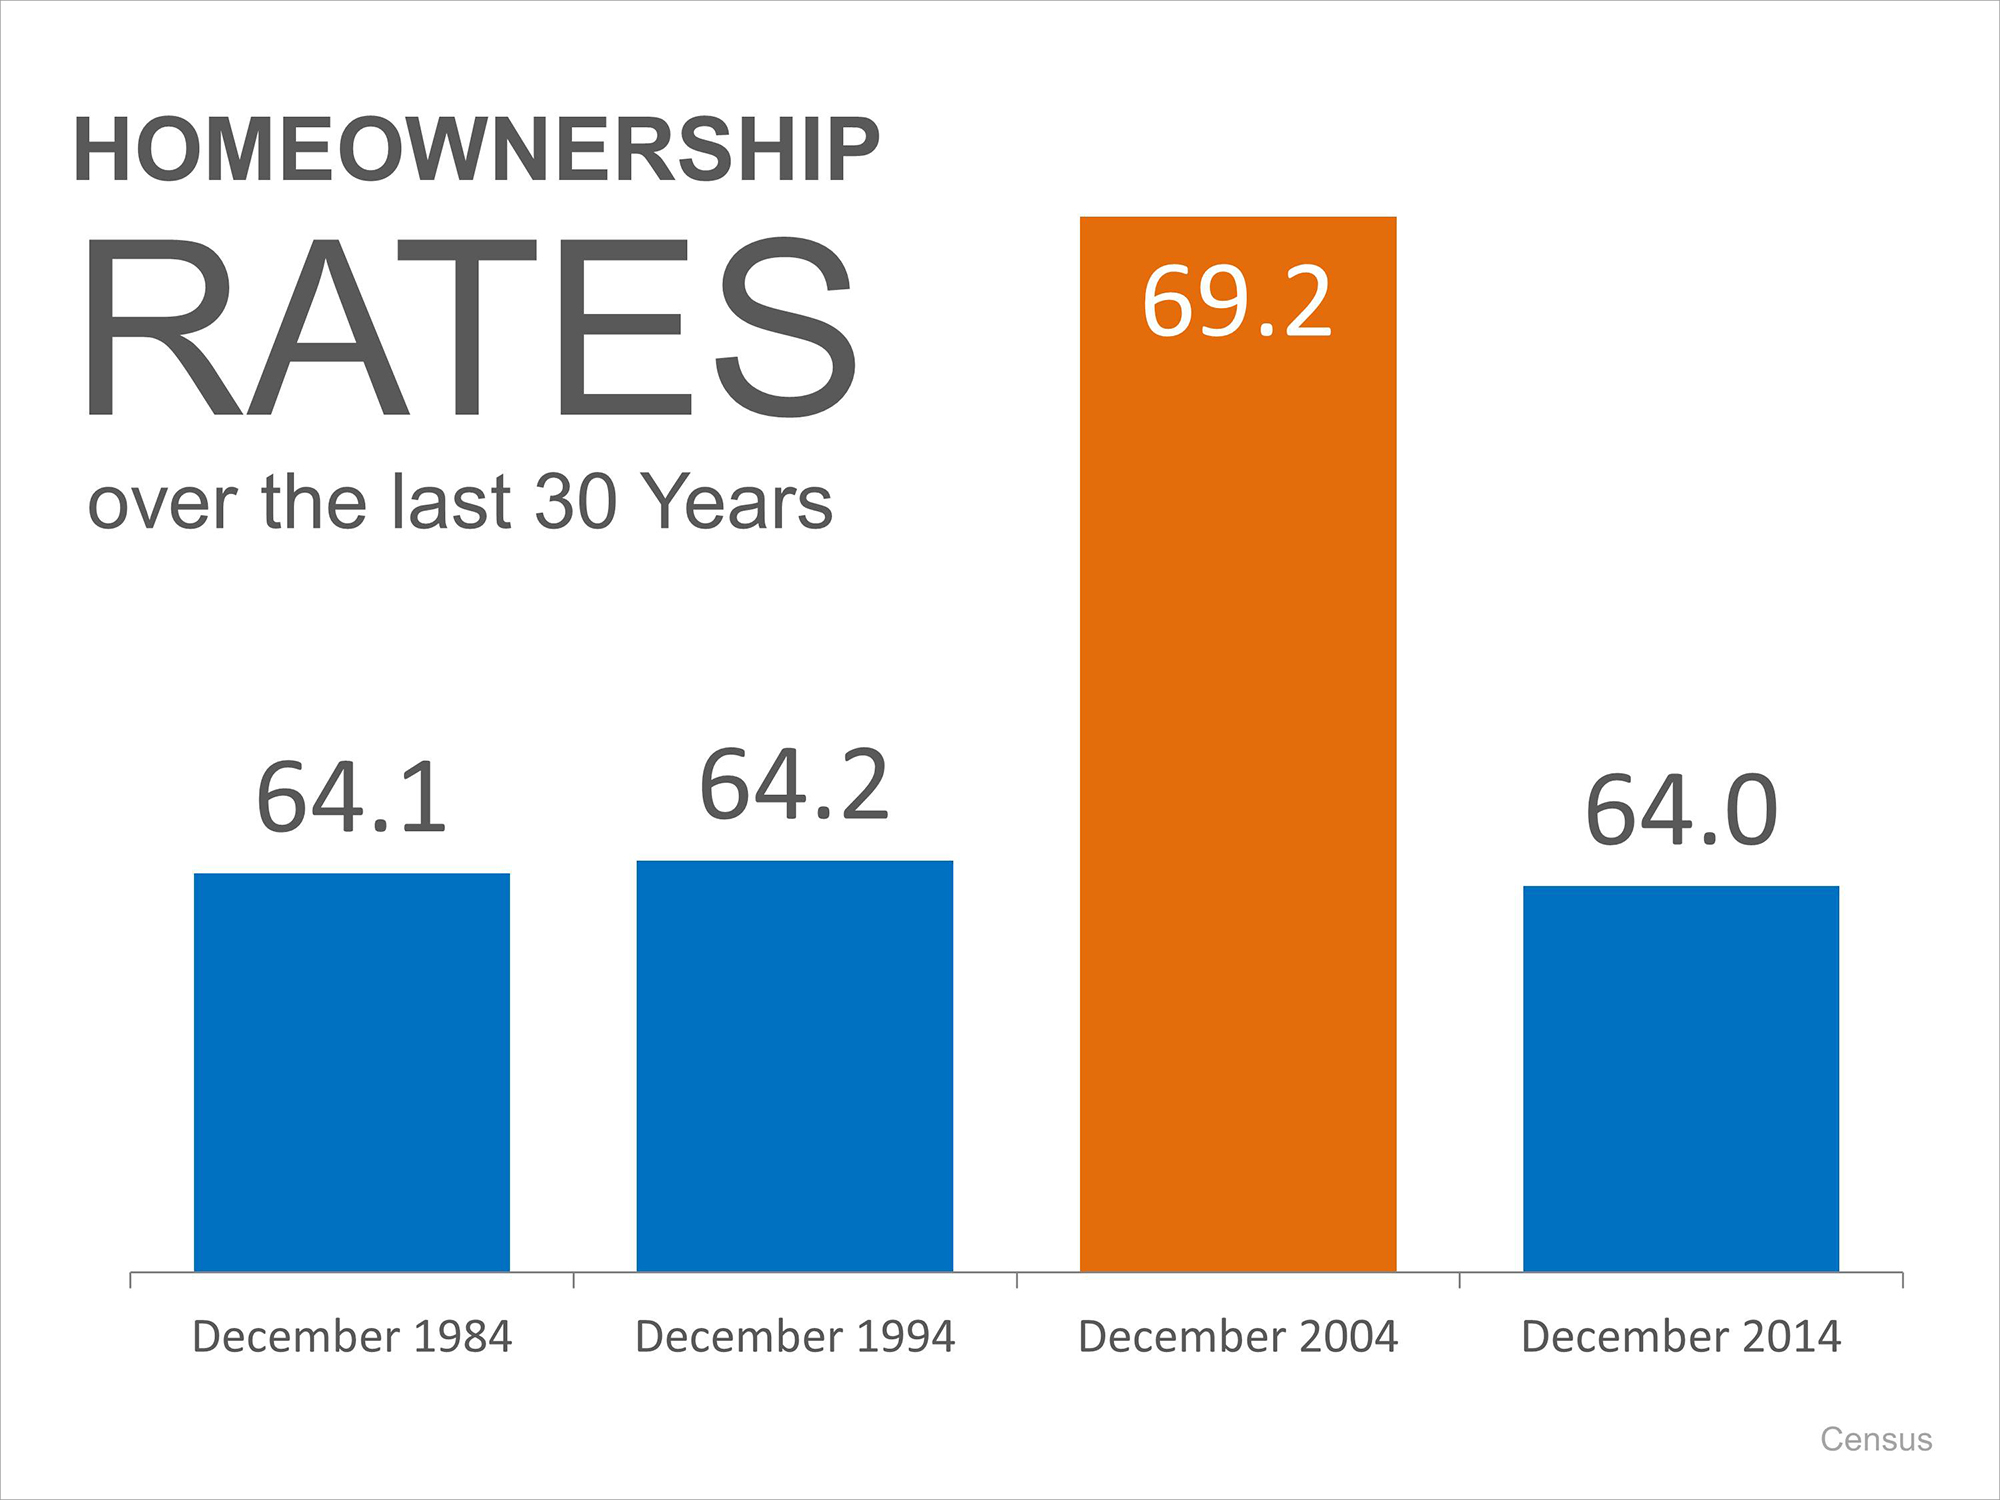
The national homeownership rate peaked in 2004, representing a 69.2% of Americans who bought vs. rented their primary residence. Many have noticed a decline in rate since then and taken that as a bad sign.
However, if you look at the national rate over the last 30 years (1984-2014), you can see that the current homeownership rate has returned closer to the historic norm. 2014 ended the year with a rate of 64% just under the rate in 1985 and 1995.
Homeownership Rates Historically | Simplifying The Market

Bottom Line

With interest rates and prices still below where experts predict, evaluate your ability to purchase a home with a local real estate professional.

Tuesday, February 17, 2015

THE GOVERNMENT IS ACTUALLY TRYING TO HELP

AFTER YEARS OF TRYING TO DISCOURAGE LENDING AND HOME OWNERSHIP THE GOVERNMENT IS MAKING IT EASIER FOR FHA BUYERS TO PURCHASE


Please before you decide whether you can afford to own or move up let's get with an actual lender and find out.  The misinformation I hear on the news is amanzing.

Monday, February 16, 2015

EITHER WAY, YOU'RE PAYING A MORTGAGE

Either Way, You’re Paying a Mortgage

Either Way You're Paying a Mortgage | Simplifying The Market
There are some people that have not purchased a home because they are uncomfortable taking on the obligation of a mortgage. Everyone should realize that, unless you are living with your parents rent free, you are paying a mortgage - either your mortgage or your landlord’s.
As a paper from the Joint Center for Housing Studies at Harvard University explains:
“Households must consume housing whether they own or rent. Not even accounting for more favorable tax treatment of owning, homeowners pay debt service to pay down their own principal while households that rent pay down the principal of a landlord plus a rate of return. That’s yet another reason owning often does—as Americans intuit—end up making more financial sense than renting.”
Also, if you purchase with a 30-year fixed rate mortgage, your ‘housing expense’ is locked in over the thirty years for the most part. If you rent, the one guarantee you will have is that your rent will increase over that same thirty year time period.
As an owner, the mortgage payment is a ‘forced savings’ which will allow you to have equity in your home you can tap into later in your life. As a renter, you guarantee the landlord is the person with that equity.

Bottom Line

Whether you are looking for a primary residence for the first time or are considering a vacation home on the shore, owning might make more sense than renting since home values and interest rates are still lower than projected.
When you are thinking about paying your own rather than a landlord's mortgage, please get in touch with me.